Reducing the capital of an Indonesian PT is not simply the reverse of a capital increase. It is a formal amendment process that can affect shareholders and creditors, so the Company Law requires shareholder approval, public notice to creditors, an objection period and Ministerial approval before the reduction is completed.
The underlying corporate framework remains Law No. 40 of 2007 on Limited Liability Companies, which the official legislation database lists as in force subject to subsequent amendments.
Capital Reduction Indonesian PT: The Short Answer
A PT can reduce its capital, but the company should first identify which capital figure is changing and why.
The Company Law’s explanation of Article 44 treats capital reduction as potentially involving authorized capital, issued capital or paid-up capital. A reduction of issued and paid-up capital can be carried out by withdrawing shares or lowering their nominal value.
The procedure is stricter than an internal bookkeeping change because creditors have a statutory opportunity to challenge a reduction that may affect their position.
What Can a PT Reduce?
A company should separate three capital concepts before drafting the RUPS resolution:
| Capital layer | Capital-reduction question |
|---|---|
| Authorized capital | Is the ceiling in the articles being reduced? |
| Issued capital | Will fewer shares, or lower-value shares, remain issued? |
| Paid-up capital | Will the capital recorded as fully paid decrease with the issued capital? |
The intended end-state should be calculated before the RUPS. That means preparing both a before and after capitalization table showing share numbers, nominal values, shareholder percentages and share classes.
A capital reduction should not be used casually to make the company’s registered figures look smaller. The commercial reason and the legal mechanism need to match.
Step 1: Approve the Reduction Through the RUPS
Under Article 44 of the Company Law, a capital-reduction resolution is valid only if the RUPS satisfies the quorum and voting requirements applicable to amendments of the articles of association.
For the first meeting, Article 88 generally requires at least two-thirds of all voting shares to be present or represented and at least two-thirds of the votes cast to approve the amendment, unless the articles impose a higher threshold.
The RUPS documentation should therefore state clearly:
- the existing capital structure
- the amount being reduced
- whether authorized, issued or paid-up capital changes
- the mechanism for the reduction
- the resulting number and nominal value of shares
- the treatment of each shareholder and share class
This is one reason capital reduction should be planned from the final cap table backward rather than starting with a desired cash or accounting figure.
Step 2: Announce the Decision to Creditors
Creditor protection begins immediately after the shareholder decision.
After approval, Article 44 paragraph (2) requires the board of directors to notify creditors by announcing the RUPS decision in one or more newspapers within seven days from the resolution.
The publication is not merely a corporate publicity step. It starts the statutory period in which creditors can review the effect of the proposed reduction and decide whether to object.
The transaction timetable should therefore reserve time for creditor review rather than assuming the articles can be amended immediately after the RUPS.
Step 3: Allow the Creditor Objection Period
Creditors then receive a statutory review period because Article 45 paragraph (1) allows them to submit a written objection, with reasons and a copy to the Minister, within 60 days from the announcement.
If an objection is filed, the process does not automatically end. The company is expected to respond and attempt to resolve the issue.
The company must answer an objection in writing within 30 days, and Article 45 permits the creditor to bring the dispute to the district court in the specified circumstances where the objection is rejected, unresolved or unanswered.
Why Creditors Matter
A reduction can change the company’s registered capital base. The statutory notice procedure gives existing creditors an opportunity to assess whether that change affects their interests before the Ministry approves the amendment.
Build the Creditor Period Into Closing
Where the reduction is linked to a restructuring, shareholder exit or other transaction, do not set the final corporate closing date as though Ministry approval will follow the RUPS immediately. The creditor timetable must be reflected in the transaction plan.
Step 4: Obtain Ministerial Approval
Capital reduction does not become merely an internal shareholder matter: Article 46 treats it as an amendment to the articles requiring Ministerial approval and ties that approval to the absence, settlement or final judicial resolution of creditor objections.
The Minister may approve the reduction where no timely written objection exists, where an objection has been resolved, or where a creditor’s court action has been rejected by a final and binding judgment.
For the current Ministry administration layer, the official legislation database lists Minister of Law Regulation No. 49 of 2025 as in force for PT formation, amendment and dissolution procedures.
The practical sequence is therefore RUPS → creditor announcement → objection process → Ministerial approval, not simply RUPS → update the cap table.
How Issued and Paid-Up Capital Can Be Reduced
For issued and paid-up capital, Article 47 paragraph (1) provides two statutory methods: withdrawing shares or reducing the nominal value of shares.
Method 1: Withdrawal of Shares
Share withdrawal removes shares from circulation as part of the capital reduction. The law permits withdrawal in relation to shares previously bought back by the company or shares belonging to a class that can be withdrawn.
The resulting cap table must show how many shares remain outstanding and whether shareholder percentages change.
Method 2: Reduction of Nominal Value
Instead of reducing the number of shares, the PT can lower their nominal value. This changes the registered capital represented by the outstanding shares while potentially leaving the share count unchanged.
The economic and shareholder consequences can differ substantially from a withdrawal, so the mechanism should be chosen deliberately rather than treated as interchangeable drafting language.
Share Classes and Equal Treatment Matter
Where the company reduces nominal value without repayment, Article 47 paragraphs (3) and (4) generally require proportional treatment across all shares of each class unless every affected shareholder agrees to the exception.
If the company has more than one share class, Article 47 paragraph (5) requires prior approval from every class whose rights would be harmed by the reduction.
This makes the share-class review essential where the articles contain preferred shares, different voting rights or another differentiated capital structure.
A reduction that appears mathematically correct at total-company level can still create a shareholder problem if one class bears a disproportionate effect without the approvals required by law.
Check the Capital Structure After the Reduction
The analysis should not stop after choosing the reduction amount. Recalculate the company as it will exist after the amendment.
The post-reduction figures should also be tested against the continuing general capital relationship because Article 33 requires at least 25% of authorized capital to be issued and fully paid.
For example, if a PT reduces its issued and paid-up capital but leaves a much larger authorized-capital ceiling unchanged, check whether the resulting ratio still satisfies that requirement.
The company should also separately review any industry-specific, investment or financing condition that requires a minimum level of capital. A corporate-law reduction should not be finalized in isolation if another applicable rule, loan covenant or commercial agreement assumes a larger capital base.
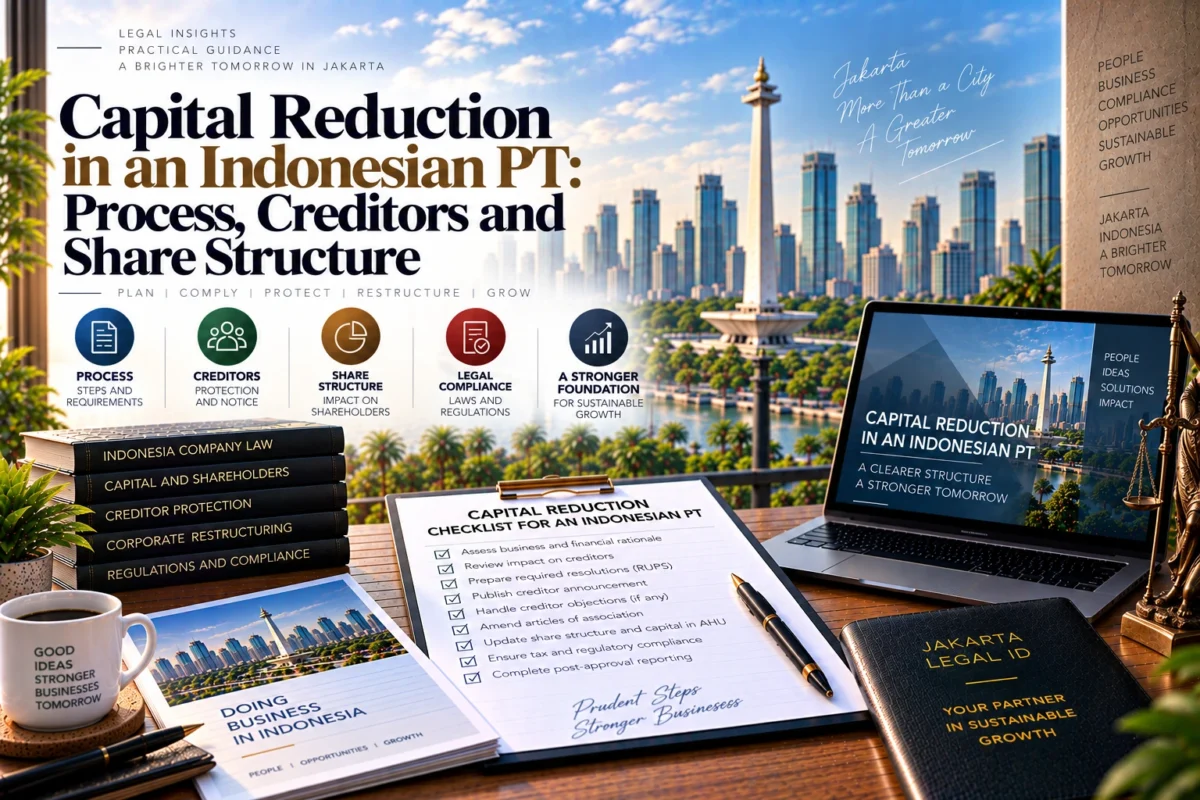
Capital Reduction Checklist
Use the following sequence before implementing a reduction:
| Review item | Question |
|---|---|
| Commercial reason | Why is the capital being reduced? |
| Existing capital | What are the current authorized, issued and paid-up figures? |
| Target structure | What will each figure be after reduction? |
| Mechanism | Share withdrawal or nominal-value reduction? |
| RUPS | Are the amendment quorum and voting thresholds satisfied? |
| Share classes | Does an affected class require separate approval? |
| Newspaper notice | Was the decision announced within seven days? |
| Creditor period | Has the 60-day objection period been completed? |
| Objections | Have any objections been answered and resolved? |
| Ministry approval | Are the conditions for approval satisfied? |
| Capital ratio | Does the resulting structure remain internally compliant? |
| Other rules | Do sector, investment, financing or contractual minimums apply? |
| Corporate records | Are the deed, shareholder register and registered data consistent after approval? |
For broader corporate-document context, Jakarta Legal ID’s notary guide for foreign investors explains how corporate resolutions and amendments fit into Indonesian company administration.
Conclusion
Capital reduction Indonesian PT is a structured corporate action, not an accounting shortcut. The shareholders must approve the amendment under the applicable RUPS threshold, the directors must announce it to creditors, creditors receive a 60-day objection period and Ministerial approval is required before the amendment is completed.
For issued and paid-up capital, the company must also choose the correct mechanism—withdrawal of shares or reduction of nominal value—and consider proportional treatment and affected share classes.
A capital reduction is therefore appropriate only when the commercial objective, shareholder mechanics, creditor process and final capital structure all align. If the objective is instead to bring new funds or issue additional shares, that belongs in a separate capital-increase analysis rather than being treated as the opposite version of the same procedure.
Plan the Capital Reduction Before the RUPS Is Signed
If your Indonesian PT is considering a capital reduction or related corporate restructuring, Jakarta Legal ID provides notary services and PT PMA/PMDN corporate setup support within its current service scope.
Request a consultation to review the proposed capital structure, shareholder resolution and corporate-amendment requirements before the reduction process begins.
FAQ – Capital Reduction Indonesian PT
Can an Indonesian PT reduce its capital?
Yes. The Company Law permits capital reduction, but it is a formal amendment process requiring the applicable RUPS approval, creditor notification and Ministerial approval.
How quickly must creditors be notified after the RUPS?
The board of directors must announce the capital-reduction decision in one or more newspapers within seven days from the RUPS resolution.
How long do creditors have to object to a capital reduction?
Creditors have 60 days from the newspaper announcement to submit a written objection with reasons to the company, with a copy to the Minister.
Does capital reduction require Ministry approval?
Yes. Article 46 treats capital reduction as an amendment to the articles requiring Ministerial approval, with approval linked to the status of creditor objections.
How can issued and paid-up capital be reduced?
Article 47 provides two principal mechanisms: withdrawal of shares or reduction of their nominal value.
Can a PT reduce only one shareholder’s nominal share value?
A nominal-value reduction without repayment must generally be applied proportionately to all shares within each class. An exception requires the consent of all shareholders whose share nominal value is reduced.
References & Sources
- Law No. 40 of 2007 on Limited Liability Companies — peraturan.go.id
- Law No. 40 of 2007 on Limited Liability Companies — Official Government Text — pajak.go.id
- Law No. 6 of 2023 Enacting the Job Creation Government Regulation in Lieu of Law — peraturan.go.id
- Minister of Law Regulation No. 49 of 2025 on Limited Liability Company Formation, Amendment and Dissolution — peraturan.go.id
Recommended Next Articles
- notary services for foreign investors and corporate amendments — jakartalegalid.com
- NIB and OSS registration guide for company data and licensing — jakartalegalid.com